
Our MCA debt calculator gives you a personalized estimate in a few minutes, covering your potential payment relief, new weekly payment range, and which path, refinancing or attorney-led restructuring, best fits your situation. Here’s what each part of your MCA debt calculator results actually means.
How the Calculator Works
The calculator walks you through three quick steps:
Step 1: Your Situation
You’ll choose the option that best fits where your business stands right now, whether that’s feeling overwhelmed by daily payments, juggling multiple stacked MCA positions, falling behind, already facing legal action from a funder, or simply exploring your options before anything urgent happens. This helps point the rest of the calculator toward the right starting assumptions.

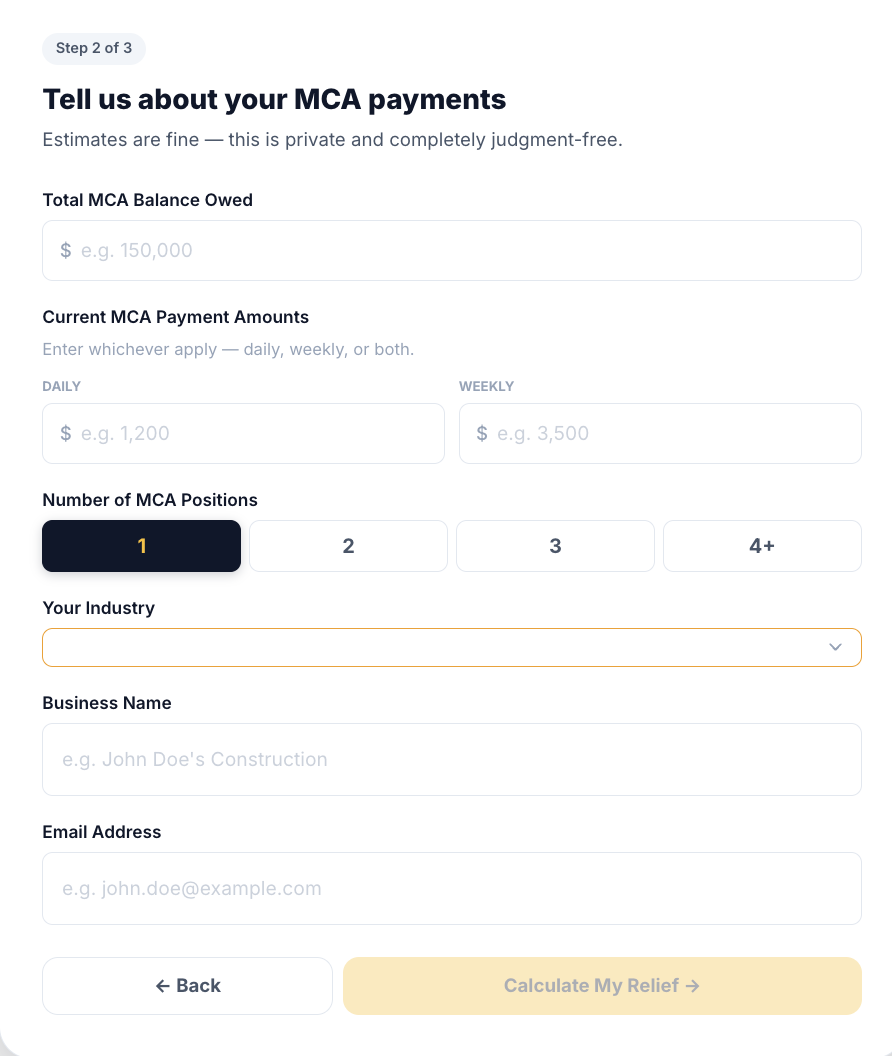
Step 2: Your MCA Payments
Here you’ll enter your total MCA balance, your current daily and/or weekly payment amounts, how many MCA positions you’re carrying, and a few basic details like your industry and contact information. Estimates are fine; you don’t need exact figures pulled from a statement to get a useful result.
Step 3: Your Results
Your results appear immediately and cover your payment relief estimate, a new weekly payment range, and a full breakdown of your current situation.
Let’s take a closer look at what the numbers mean.
What Each Result Means
Your Payment Relief Estimate
This is the headline number, shown as a percentage. It reflects the typical reduction of your current weekly payment total for the path you’ve been matched to.
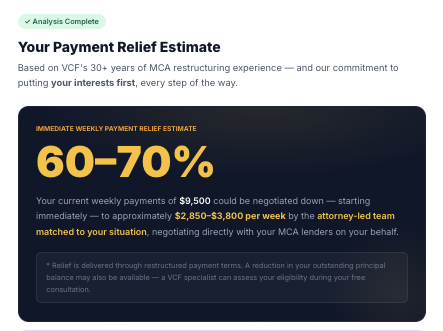
Restructuring cases typically see 60-70% relief. If your situation qualifies for refinancing instead, your estimate may reflect the higher 65-85% range refinancing usually delivers.
Either way, this is a starting estimate based on typical outcomes, rather than a guarantee. Your final numbers depend on your actual lenders and negotiation.
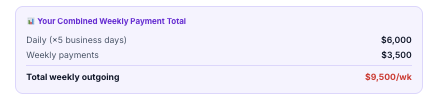
Your Combined Weekly Payment Total
This is your current math: your daily payments multiplied by five business days, plus any weekly payments, added together. It’s the baseline your relief estimate is calculated against.
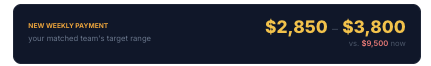
Your New Weekly Payment Range
This shows the target range your matched team would aim to negotiate your payments down to. It’s a range rather than a fixed number because the final terms depend on the specific lenders involved and how negotiations play out.
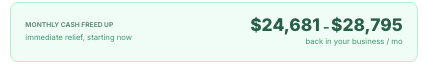
Monthly Cash Freed Up
This translates your weekly savings into a monthly figure, giving you a clearer sense of how much cash could return to the business each month once new terms are in place.
Your Situation Overview
This section summarizes what you told us: your payment pressure level, how many MCA positions you’re carrying, whether your payments are daily, weekly, or both, your industry, and confirmation that there are no upfront fees. It also shows your matched team, which tells you which path the calculator has pointed you toward based on your answers, attorney-led restructuring or refinancing, along with how quickly you could be enrolled and protected if you moved forward.
If your matched team is attorney-led restructuring, see Benefits of Attorney-Led Restructuring for what that path entails.
If you’re matched toward refinancing, see Why VCF Tries Refinancing First.

What Happens After You See Your Results
Your results aren’t a commitment. The next step is a free consultation, where a specialist reviews your specific situation in more detail and confirms which path actually fits: refinancing, attorney-led restructuring, or a closer look if your situation is more complex than the calculator alone can capture. There’s no pressure to decide anything on the call, and no obligation to move forward afterward.
Ready for the next step? Our friendly and experienced team offers fast, judgment-free support. Book a free, no-obligation consultation today.
MCA Debt Calculator FAQs
No. They’re an estimate based on typical outcomes for businesses in similar situations. Your final numbers depend on your specific lenders and the outcome of negotiations.
Yes. What you enter is used to generate your estimate and, if you choose to continue, to connect you with a specialist for your free consultation. It isn’t sold to third parties or used to add you to unrelated marketing lists.
Nothing beyond a few numbers you likely already know, your total MCA balance, your daily or weekly payment amount, and how many MCA positions you’re carrying. If you’d rather prepare more thoroughly before your free consultation, the 3-Step Foundation Guide walks through what to gather, and the MCA Health Check is a quick way to see how sustainable your current debt load is.
Not at all. The calculator doesn’t require exact figures to give you a useful result, so estimates are fine to use.
That’s normal. You can run the calculator again with updated figures at any time; there’s no limit, and your consultation will always be based on your most current numbers rather than an old estimate.
It won’t. The calculator only asks for basic details about your MCA balance and payments; it doesn’t run a credit check or pull your credit score.
No. Getting your results doesn’t commit you to working with us. The next step, a free consultation, is also no-obligation and totally judgment-free.